Sustainability vs Cost: How Should a Project Manager Decide?
The question rarely arrives as a debate about values. It usually arrives as a line on a cost-reduction schedule: swap the specified lower-carbon option for a conventional one and bring the forecast back inside budget. The saving is immediate, measurable and sits squarely within the project manager's accountability. The sustainability benefit is spread over years, often lands in someone else's budget and resists being expressed as a single figure. Framed that way, cost wins almost every time, and not always because it should.
So how should sustainability and cost be balanced? A project manager should rarely settle the trade-off on instinct, and should never let it be settled silently. The work is to put both options on the same footing, over the same period, with the uncertainty visible, and to make sure the decision is taken by whoever holds authority for its consequences. Sometimes the cheaper option is the right one. The failure is not choosing cost; it is choosing it without anyone seeing what was given up.
Whose cost, and over how long?
Many arguments framed as sustainability versus cost are really arguments about accounting boundaries. The project budget captures what it costs to deliver. It rarely captures what the finished asset, system or service will cost to run, maintain, repair and eventually dispose of. More efficient plant, better insulation or lighting controls may add capital cost while reducing operating cost for years afterwards. Compare the options on capital cost alone and the conventional choice looks cheaper almost by definition, because the comparison has been drawn around the one period in which it is.
A fairer comparison starts with three questions. Over what period will the organisation live with this decision? Who pays the additional cost, and who receives the saving or benefit? How confident are the estimates on each side? Whole-life costing is familiar territory to experienced estimators and facilities professionals, yet it is often skipped under pressure because the operating figures belong to another department and take effort to obtain. The project manager does not need to become a cost consultant, but does need to notice when a comparison has been drawn too narrowly to support the decision being made with it.
The PMBOK® Guide - Eighth Edition gives this a useful anchor. Section 3.7 of The Standard for Project Management sets out sustainability as a principle to be integrated within all project areas, which is a very different position from treating it as a compliance check near the end. Read that way, sustainability is not only environmental. Social effects and long-term economic viability belong in the same conversation, so "sustainability versus cost" is partly a false opposition: an option that cuts carbon but leaves the organisation with something it cannot afford to operate is not a sustainable choice either.
Sustainability is not an automatic trump card
Some writing on this subject implies that the sustainable option should always prevail. That is not a defensible stance for a project manager. Sustainability is a legitimate decision factor, and often an under-weighted one, but it sits alongside safety, legal obligations, the value the project exists to create and whether the proposed solution will actually work. A project manager who challenges a weak sustainability proposal is doing the job just as surely as one who challenges a careless cut.
What helps is recognising which kind of sustainability item is on the table, because each is handled differently. Some are required: a regulatory obligation, a planning condition, a contractual commitment or an organisational policy that applies to the project. These are not trade-offs the project can make, and if they turn out to be unaffordable, the problem belongs with governance and the business case rather than with a value-engineering list. Others are committed: the business case or benefits plan promised them, and the sponsor may have secured approval partly on that basis. Removing one changes what the project was authorised to deliver, so it needs to pass through change control rather than a budget meeting. The rest are discretionary, and this is where genuine cost-benefit judgement applies.
Even discretionary items deserve scrutiny in both directions. Some sustainable options pay back well; some never do within any realistic horizon. Some rely on materials or suppliers with a limited track record, which moves the question from cost into risk. Some deliver benefits that are real but modest, and the honest answer may be that the same money creates more value elsewhere. The discipline is the one applied to any other investment decision: understand what is being bought, what it will return, how certain that return is and what it displaces.
Putting the decision in front of the right person
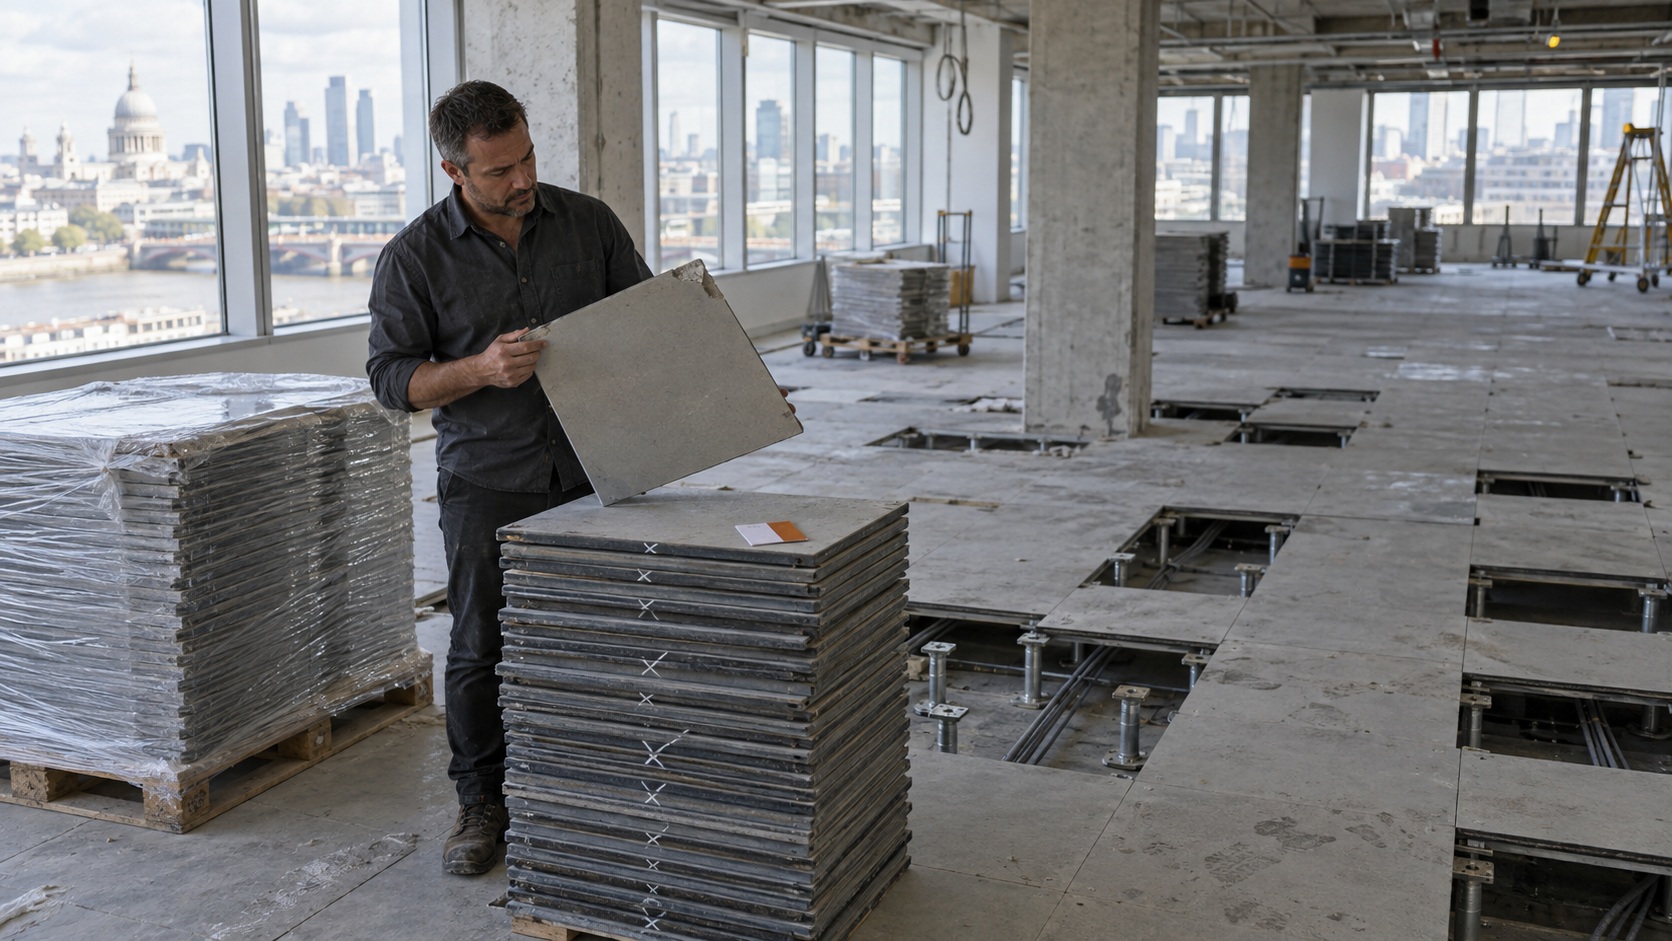
Consider a fictional refurbishment of a four-storey office building that a regional housing association intends to occupy for at least fifteen years. The approved business case states that existing materials will be reused "where practical", and the specification calls for the raised access floor panels to be lifted, cleaned and relaid. Partway through strip-out, the contractor raises a problem. A sample of lifted panels has been graded, and around a third have chipped edges or damaged surfaces. Every panel has to be lifted, inspected, cleaned and graded by hand, and the contractor will not warrant reused panels on the same terms as new ones. Its proposal is to replace the whole floor with new panels at a fixed price, which works out cheaper than the labour-heavy reuse route once the rejects are replaced. The project is already forecasting an overspend.
The tempting response is to accept the saving and move on. A more competent one starts by asking what kind of item this is. "Where practical" makes it a commitment with a qualifier attached, and the project manager is not the right person to decide unilaterally what the sponsor meant by practical. Then comes the comparison. The saving from buying new is certain and sits on the project's ledger; the embodied carbon benefit of reuse is real but appears nowhere in the project's figures; the warranty difference is a risk the facilities team will carry for years. The project manager asks for a wider sample to test whether a two-thirds pass rate holds across the whole building, and asks facilities what the weaker warranty would mean for maintenance.
Timing matters as well. Once rejected and surplus panels go into a skip, the reuse option has gone for good. So the project manager puts disposal on hold and takes three options to the sponsor: fund reuse in full and find the difference elsewhere in the budget; accept new panels throughout and formally amend the benefits position; or reuse only the panels that pass grading and buy new for the rest, with a cap on grading labour. The paper carries a recommendation and the reasoning behind it, and the outcome is recorded in the decision log.
Any of those outcomes could be defensible. What would not be defensible is the version where the swap is agreed in a site meeting, recorded as a cost saving, and discovered a year later by a sustainability lead trying to work out why the refurbishment reported none of the reuse its business case described. The questions travel well beyond floors. Is this required, committed or discretionary? What does each option cost over the period the organisation will live with it, and who pays? How reliable are the figures? What is lost if the choice is deferred? Whose decision is it?
Balancing sustainability and cost before the pressure arrives
The most expensive moment to discuss sustainability is when the budget is already under strain, because every sustainable feature then competes directly with the overspend. Late cost-reduction exercises tend to remove sustainability items first, not because they are least valuable but because their benefits sit outside the project's accounts and their removal is easy to describe as having no effect on scope. The trade-off is far smaller when it is settled earlier: in option appraisal, where whole-life cost can be compared before a design is chosen; in the business case and benefits plan, where commitments can be written clearly enough to act on; in procurement, where evaluation criteria can reward more than the lowest capital price; and in governance, where a threshold can state that any change to a sustainability commitment goes to the sponsor.
The development approach shapes where this lives. On predictive delivery, sustainability requirements usually sit in the specification and baseline, and changes to them follow the change process like any other. On adaptive delivery, they can sit in acceptance criteria or be weighed during backlog prioritisation as the product evolves. On hybrid work, both may apply to different parts of the same project. None of these makes the trade-off disappear; each gives it a proper place to be decided.
For a PMP® candidate, the current PMP Examination Content Outline does not give sustainability a domain of its own. It names sustainability within four specific enablers: planning critical information requirements, managing cost of quality, confirming compliance requirements and managing sustainability risks. The helpful preparation habit is to recognise that a sustainability scenario is normally a finance, quality, compliance, risk or governance scenario underneath, and to reason through it with the same discipline: understand the situation, check what has been committed and who holds authority, analyse the options, then act or escalate proportionately. Trade-offs of this kind feature regularly in Omega's PMP® Exam Preparation, where the emphasis falls on reading commitments, authority and evidence before settling on a response, rather than on spotting whichever option sounds more responsible.
On a live project, the test is simple to state and harder to apply. When a sustainability feature is about to be cut or added, could you explain to the sponsor, and later to the people who operate the result, what was compared, over what period, who bears the cost and who agreed? If so, the decision can be defended whichever way it went. If not, cost has probably won by default rather than by judgement.
Andre Malowney
Interested in going further?
Sustainability trade-offs reward the project manager who can tell a firm commitment from a discretionary choice and route each to the right decision-maker. Structured PMP preparation builds that habit through repeated scenario practice, so the reasoning holds when the budget pressure is real.
For the sustainability principle behind this decision, and the finance and risk thinking it draws on, the PMBOK® Guide Eighth Edition is the reference to keep close.
Ad · Amazon affiliate link.
References
A045: Sustainability in Project Management: What It Means in Practice
A048: Sustainability vs Schedule: When Faster Is Not Better
A046: Sustainability and the PMP Exam: What You Actually Need to Know
A055: The Stewardship Lens: Connecting AI, Sustainability and Ethics
A204: How to Think Through an AI or Sustainability PMP Scenario
PMP and PMBOK are registered marks of the Project Management Institute, Inc.